1 October, 2026 | Shanghai, China
Asia is not one market. Treating it as one is the fastest way to burn €50,000 and 12–18 months on a market that was never going to work. Craft brands face a specific problem: not enough bandwidth to chase every opportunity, not enough capital to waste on the wrong one. The solution is not more information — it is a structured way to rank markets before you commit.
This article gives you a working framework: five dimensions to score, four market profiles written from a compliance perspective, eight product archetypes mapped to their strongest first market, and the three mistakes that sink the majority of first-time Asian entries. By the end, you will have a first answer to the question every exporter asks: which market do I start with?
If you already have inbound enquiries from one or two Asian distributors and want a fast reality check on which to prioritise, our free 20-minute compliance snapshot does exactly that — book one here.
Why "Asia" Is Not One Market
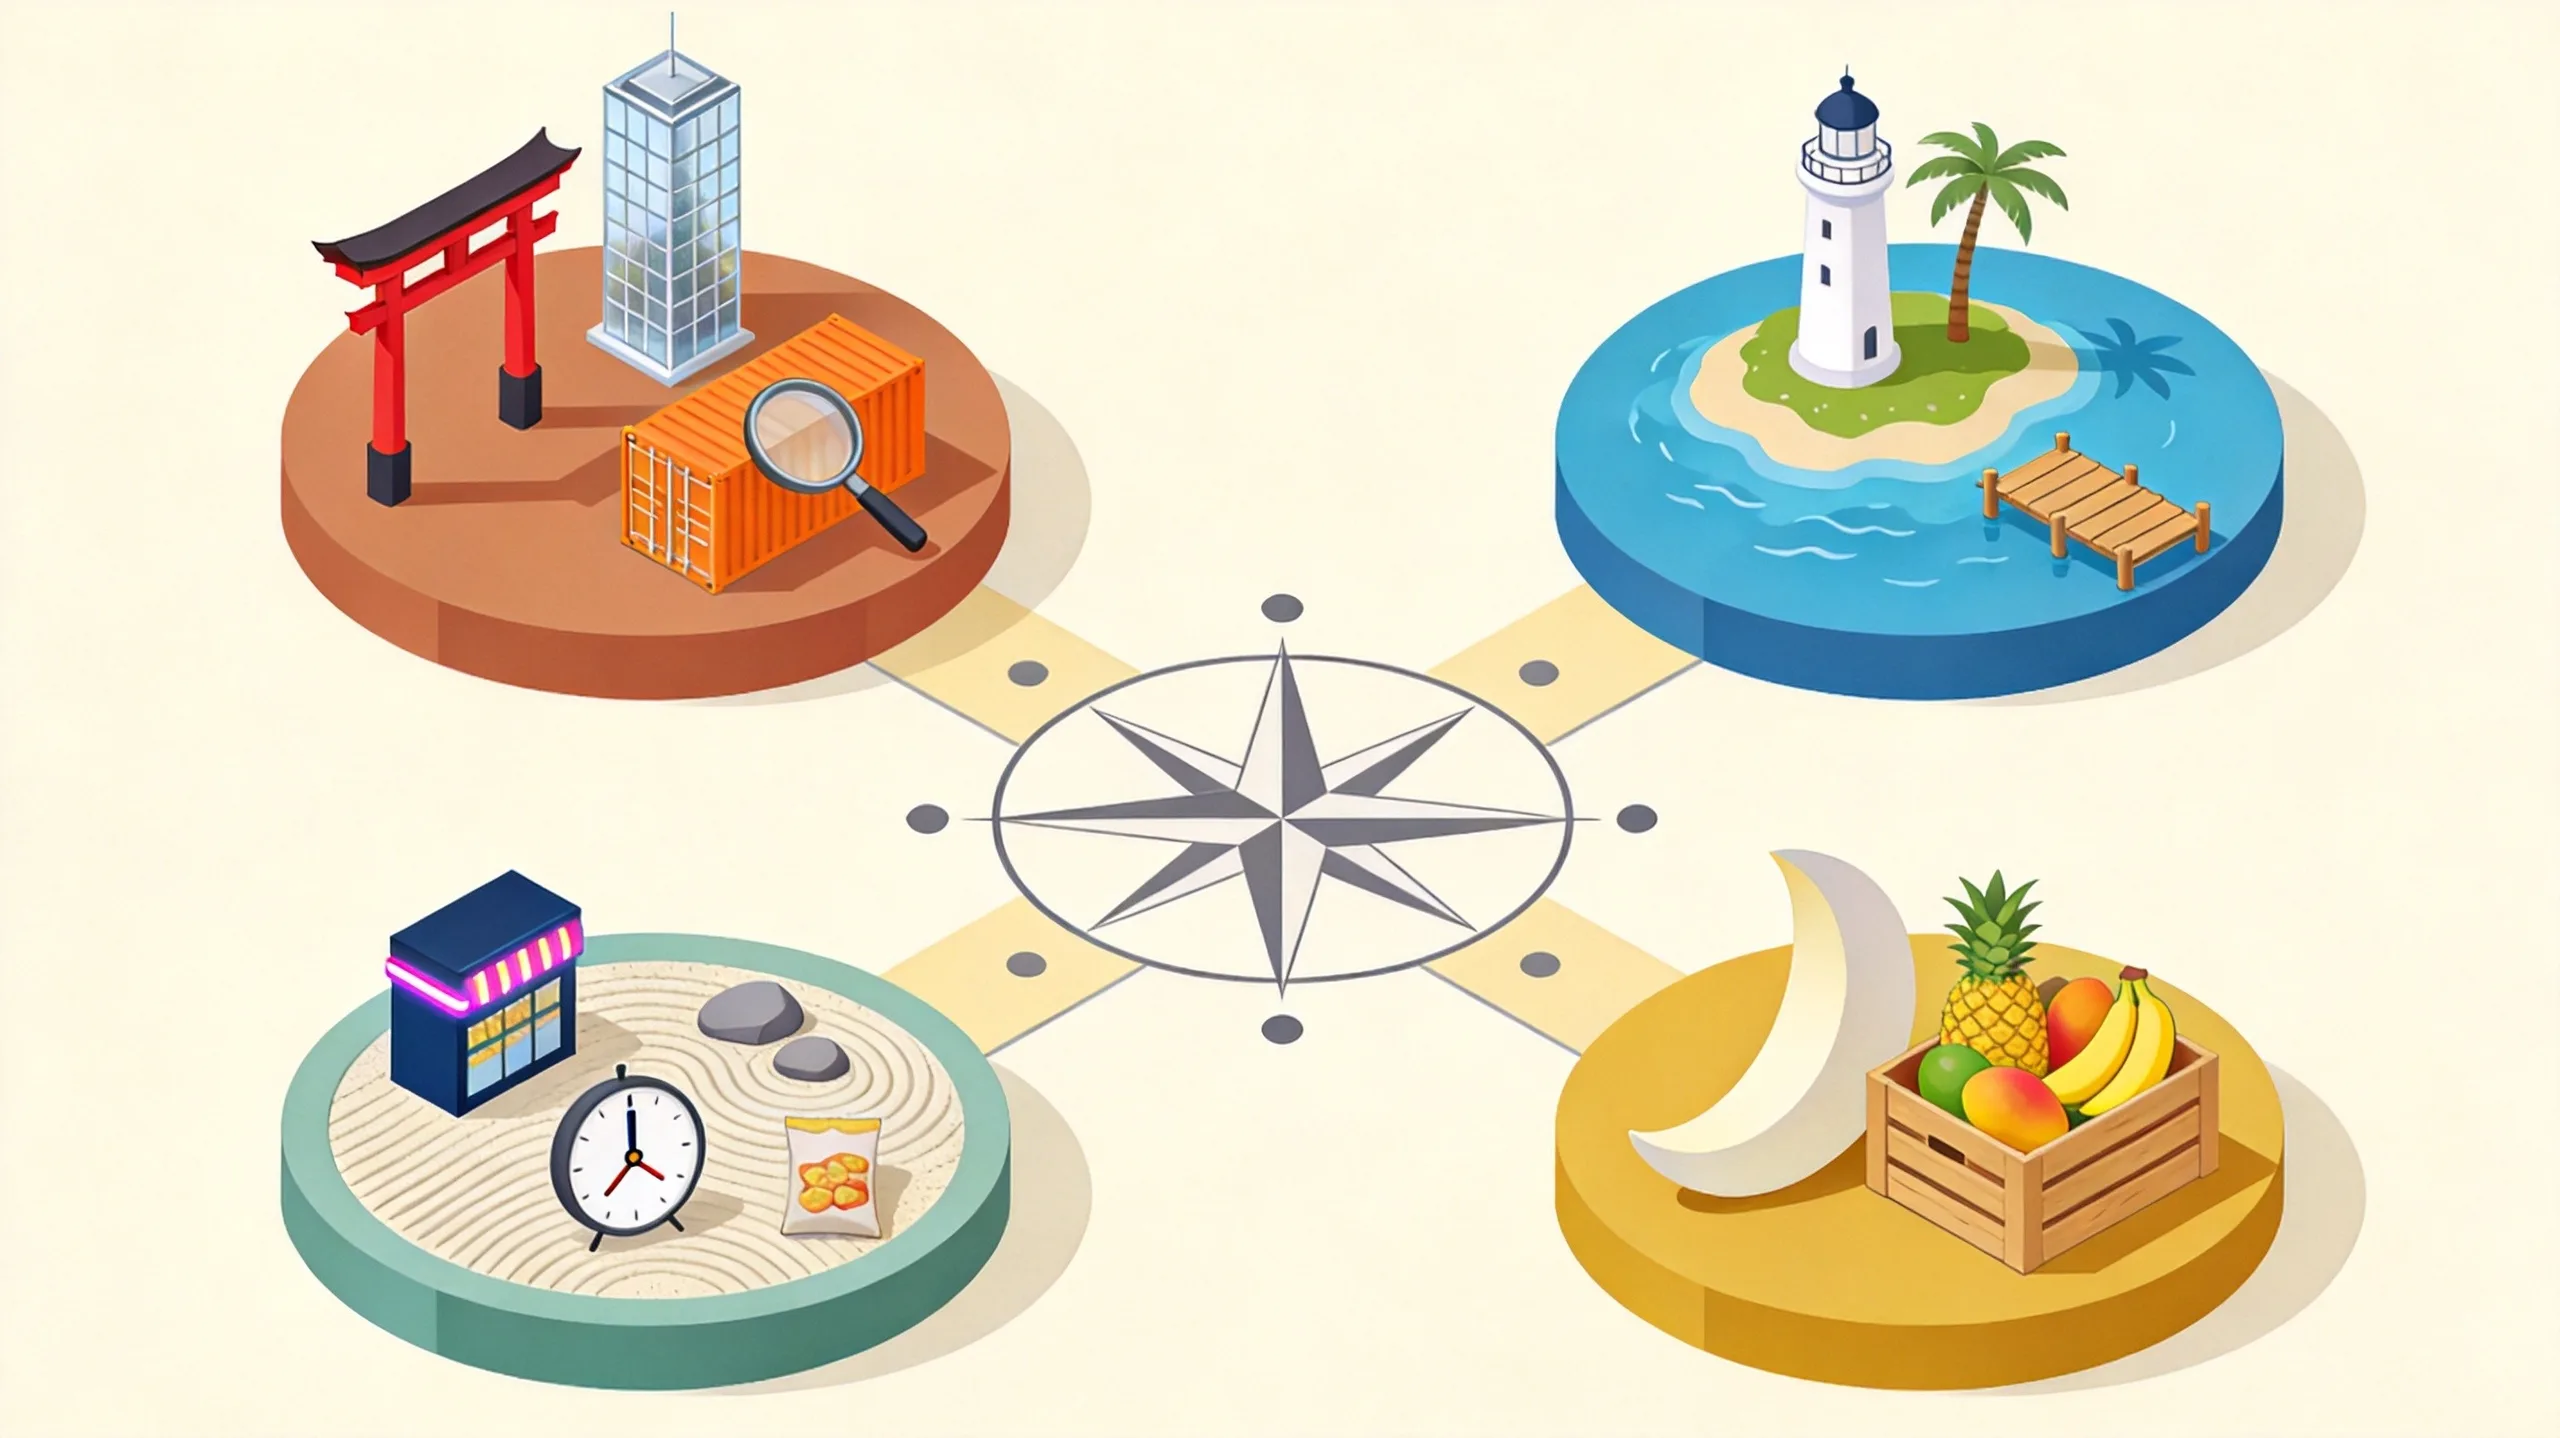
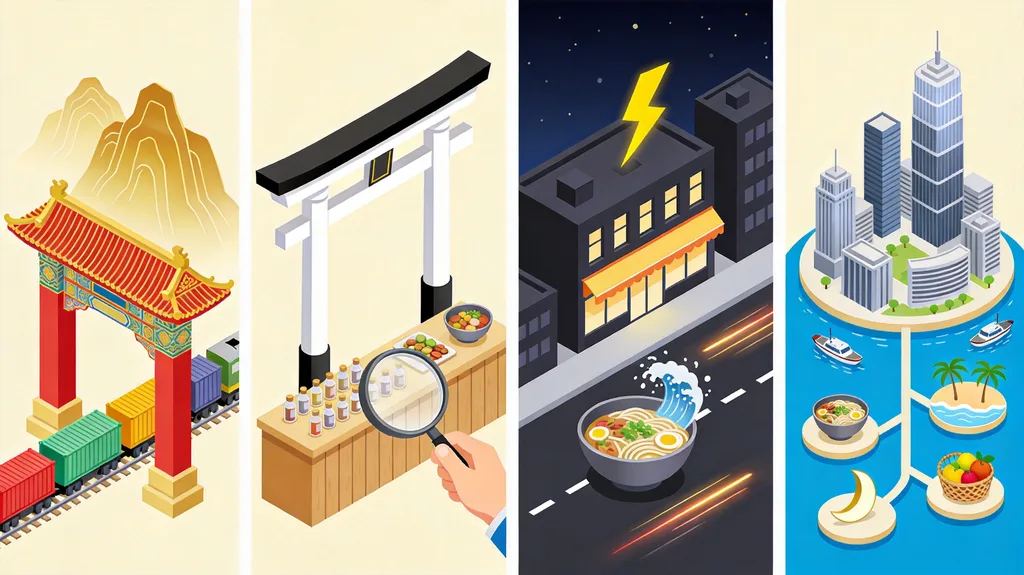
Four distinct market families exist across Asia, each with different rules, channels, and consumer expectations:
- Greater China (Mainland China, Hong Kong, Taiwan) — the largest prize, the highest barrier. Registration-heavy, label-strict, but enormous scale.
- Japan and Korea — premium pricing, sophisticated consumers, strict additive and labelling rules. Fast entry is possible if compliance is handled correctly from day one.
- Southeast Asia (Singapore, Vietnam, Thailand, Indonesia, Malaysia, the Philippines) — fragmented, varying regulatory maturity, a fast-growing middle class. Singapore is widely used as a regional springboard.
- Rest of Asia (India, the Gulf markets, Central Asia) — long-term plays, not first-market material for most craft brands.
Choosing the wrong family costs more than a delayed launch. It costs the capital you needed for the right market. A 12-month runway is a fixed resource: spend it in a market where your product can actually clear customs, not in the market with the largest GDP.
The Five Dimensions
Score each candidate market 0–5 on each dimension. Total out of 25.
| Dimension | What it measures | Anchor for 0 | Anchor for 5 |
|---|---|---|---|
| Tariff | Effective duty burden on your specific product | Prohibitive (50%+) or quota-blocked | Zero duty (FTA or unilateral preference) |
| Regulation | Registration complexity, timeline, and cost | 3–5 years, factory audits, novel-food dossiers | Straightforward notification, under 3 months |
| Channel | Availability of your natural distribution path | No identifiable importer category for your SKU | Mature on- and off-trade with importers actively prospecting |
| Size × Price | Realistic addressable revenue at your price point | Negligible premium segment | Large, price-supportive premium segment with proven imports |
| Time-to-sale | Months from decision to first cleared shipment | 18+ months | Under 6 months |
The weights matter. A cash-constrained brand should over-weight Regulation and Time-to-sale. A well-funded brand with an 18-month runway can over-weight Size × Price. If you are still raising your next round and need a reference account fast, channel readiness and time-to-sale are what make or break the entry; if you are building a 5-year Asian beachhead, tariff structure and regulatory ceiling matter more.
Run the numbers honestly. It is common for a brand with a 12-month runway to discover that the market with the biggest consumer pull is not the market they can realistically ship to in that window — and that is useful information, not a defeat.
Profile A – China: The Prize That Demands Patience
Scores: Tariff 3, Regulation 2, Channel 3, Size × Price 5, Time-to-sale 2. Total: 15/25.
China offers scale no other Asian market matches. Premium imports are growing in tier-1 cities, and categories that were niche five years ago — craft spirits, speciality olive oil, healthy snacks — now have dedicated shelf space in premium retailers and on e-commerce. But the compliance surface is wide, and it got wider on 1 June 2026.
Under GACC Decree 280, overseas food producers must be registered in CIFER (the Customs Imported Food Exporter and Importer Registration system) before their product can be declared. Alcohol products are not on the 17-category recommended list for official recommendation-by-competent-authority, so most craft distillers and food producers register via the self-service path. Registration is per production facility, not per brand; one SKU does not cover your whole portfolio. The registration number must appear on the Chinese back label.
Chinese labelling itself is governed by GB 7718-2025, released in March 2025 and taking effect 16 March 2027. The new standard introduces a dedicated chapter for imported foods, mandatory allergen labelling for eight major allergens, dual-date marking (production date + expiry date), and a requirement that the overseas producer's Chinese registration number be printed on the label. Products manufactured before 16 March 2027 may still circulate under the older GB 7718-2011 within shelf life, but new packaging orders placed now should be built against the 2025 version — otherwise you will relabel within a year.
Additive compliance is governed by GB 2760, which operates as a positive list: only additives explicitly listed for your food category are permitted, at the dosage specified. Ingredients approved in your home market are not automatically approved in China.
Realistic timeline: 6–12 months for a compliant first shipment, assuming no novel ingredients.
Suits: Brands with a 12+ month runway, willingness to invest in compliance up front, and a product category with existing consumer awareness in China (chocolate, olive oil, craft spirits, wine, dairy, baby food all have established premium segments).
Does not suit: Brands needing revenue in under 6 months, products containing novel ingredients not yet approved in China, or brands without a Chinese-speaking importer who can drive label review. One lighter pathway worth knowing: cross-border e-commerce (CBEC) eliminates the need for a Chinese entity, replaces full GB 7718 physical labelling with electronic product information, and cuts the effective VAT burden by roughly a third. It is not a loophole and has its own compliance traps, but it can reduce time-to-first-sale to 3–5 months for qualifying SKUs. We break down the CBEC route — qualification rules, bonded-warehouse mechanics, platform requirements, realistic budgets, and hidden compliance risks — in this dedicated guide.
A common misconception: Hong Kong is not a back door into mainland China. Hong Kong has its own labelling and registration regime (lighter, faster), but product moving from Hong Kong into the mainland must still clear full GACC/GB compliance as if it were shipped directly. Hong Kong is a legitimate first market in its own right; it is not a shortcut.
Profile B – Japan: Premium Pricing with the Strictest Additive Rules
Scores: Tariff 4, Regulation 3, Channel 4, Size × Price 4, Time-to-sale 3. Total: 18/25.
Japan pays premium prices for quality imports. The channel structure is mature, importers are professional and specialised by category, and consumers pay a meaningful premium for provenance and clean labels. If your product is well-made and positioned at a premium price point, Japan is often the most forgiving market in Asia on margin.
But Japan's positive list for food additives is the tightest in Asia. If your product contains a preservative, colour, or processing aid that is not on Japan's Designated Additives list or the Existing Food Additives list, it cannot enter — full stop. There is no "common use in country of origin" exception. We saw this firsthand in 2025 with a botanical liqueur held in Yokohama for six weeks because it carried natamycin, a preservative permitted in the distiller's home market but not on Japan's approved list. The importer ultimately had to re-formulate for the Japanese SKU. For the full Japan import process from HS classification through MHLW notification and labelling, see Japan Food Import Requirements: A 6-Step Compliance Guide for EU Exporters.
The October 2026 liquor tax window is relevant if you sell alcohol. On 1 October 2026, Japan's multi-year liquor tax unification reaches its final stage: the per-350ml tax on beer falls by ¥9.10 (from ¥63.35 to ¥54.25), while low-malt happoshu and "third-category" beer rise by ¥7.26 to meet the same rate. Canned chūhai and RTDs rise by ¥7 per 350ml can. For imported spirits, whisky, and wine, the rates are unchanged — wine and sake were unified at ¥100,000 per kilolitre in the October 2023 reform, and distilled spirits are outside the scope of this round. For craft beer importers, October 2026 is a net positive: domestic beer becomes slightly cheaper at retail, which lifts the whole category. For importers of low-ABV canned cocktails, the tax gap against beer narrows but does not close.
For non-alcohol food, the core compliance gate is the Food Sanitation Act and the MHLW positive list; processed foods require an import notification filed by the licensed importer at the quarantine station, and labels must follow the Food Labelling Act (Japanese language, allergen marking for 28 specified items, additive listing by designated name).
Realistic timeline: 4–8 months with a licensed Japanese importer already in place. Without one, add 3–6 months of distributor search.
Suits: Products with clean labels (no non-designated additives), premium positioning, a clear origin story, and an importer who already handles your category.
Does not suit: Products relying on preservatives or colours not on Japan's positive list, or brands that need to ship in under 4 months with no importer relationship.
Profile C – Korea: Fastest Win for Trendy, RTD, and Health Products
Scores: Tariff 4, Regulation 3, Channel 4, Size × Price 3, Time-to-sale 4. Total: 18/25.
MFDS (Ministry of Food and Drug Safety) registration for most processed foods is straightforward via the Imported Food Information MARU portal; customs clearance is quick when paperwork is in order, and convenience-store and social-commerce channels can take a product from unknown to top-seller in weeks.
For alcohol specifically, the Korean importer must hold a liquor import licence — and that licence is category-specific. A licence for wine does not cover beer; a licence for beer does not cover distilled spirits. Confirming your importer holds the correct licence class for your product is not a formality; it is the single most common reason alcohol shipments stall at Busan. Korea also operates a tiered precision-inspection system: products with no prior non-compliance history go through document review and random sampling; products with a non-compliance record face mandatory precision inspection for up to five consecutive shipments, with costs borne by the importer.
Korea is the trend amplifier of North Asia. Social media-driven food crazes move import volumes in ways most exporters have not seen in other markets. According to MFDS's 2026 Imported Food Inspection Yearbook, Korea imported food worth USD 36.6 billion in 2025, across 874,928 consignments from 165 countries — a 3.3% increase in consignment volume and a 2.4% increase in value year-on-year. Processed foods accounted for 35% of import volume by weight. Import volumes of kadaif pastry and pistachio (the core ingredients behind the viral Dubai chocolate dessert trend) surged by 340, and matcha imports rose 290%, both driven almost entirely by social commerce and idol-driven marketing. RTDs and health-oriented snacks continue to be the fastest-growing import categories.
It is not all upside: that same trend cycle means products that rise fast also fade fast. The Dubai chocolate boom that emptied shelves in 2024 had largely cooled by early 2025; the "ddu-jjon-ku" (Dubai chewy cookie) variant dominated winter 2025–26 and was already in decline by spring 2026. Korea rewards speed but punishes late entrants.
Realistic timeline: 3–6 months for processed foods; 4–8 months for alcohol once the correct-category importer is confirmed.
Suits: Trendy products, RTD beverages, health snacks, premium confectionery, and brands that can ship quickly to meet a trending window.
Does not suit: Products requiring lengthy novel-food approval, products with genetically modified or unauthorised functional ingredients, or brands that cannot supply within a 6–8 week order cycle.
If you are wondering whether your specific product class fits Korea's fast-cycle model — or whether your Korean partner's liquor licence actually covers your SKU — send us the product spec sheet, and we will give you a straight answer.
Profile D – Southeast Asia
Southeast Asia is five markets, not one. Treat it as a bloc, and you will misallocate entry spend.
Singapore — the springboard. Zero duty on most food and beverage categories, English-language labels accepted (with supplementary labelling for certain regulated categories), mature import infrastructure, and a concentration of regional distributors who use Singapore as a hub. Entry is fast — 4–8 weeks for most processed foods. The market is small, so treat Singapore as a proof point, a regional reference customer, and a logistics hub, not as a revenue market on its own.
Vietnam. A fast-growing middle class and a young, urban consumer base make Vietnam an attractive medium-term play, but the regulatory environment is tightening. Alcohol is governed by QCVN 30:2026/BCT, issued by the Ministry of Industry and Trade (Circular 39/2026/TT-BCT, 30 June 2026) and taking effect 1 January 2027, replacing the older health-ministry standards. The new national technical regulation sets methanol, SO₂, diacetyl, heavy-metal,l and microbiological limits by product category (beer, wine, spirits, fruit wine, vodka/white blended spirit), and requires conformity declaration before circulation. Products that completed self-declaration before the circular was issued may continue using their existing declaration through the end of 2027 (barring food-safety alerts). If you are entering the Vietnamese alcohol market now, build the dossier against QCVN 30:2026/BCT, not against older BYT standards.
Indonesia. BPOM (National Agency of Drug and Food Control) registration is mandatory, and halal certification under BPJPH is required for any product containing animal-derived ingredients (including gelatin, rennet, lard, and certain additives). Lead times for BPOM registration commonly run 6–12 months. Product registration is tied to the Indonesian importer; switching importers means re-registering.
Thailand. Thai FDA import licensing and Thai-language labelling are required. Alcohol has an additional excise and licensing layer. Lead times are moderate (3–6 months for non-alcohol), but importer quality varies significantly.
Malaysia. JAKIM halal certification is the strictest in Southeast Asia and is mandatory for all products containing animal-derived ingredients (excluding pork, which is prohibited from halal channels altogether). Malaysia's halal standards require slaughterhouses and processing facilities to be dedicated exclusively to halal production — effectively excluding many meat and dairy manufacturers who run mixed lines. If your product is halal-certified by a JAKIM-recognised body, this opens the entire Muslim consumer segment, which is the majority of the market; if not, you are limited to non-halal retail channels concentrated in the Klang Valley and tourist areas.
The Philippines is the seventh major ASEAN consumer market and is comparatively open for shelf-stable processed foods (FDA registration, English-language labels accepted with minimal supplementary information), but weaker IP enforcement and a highly fragmented retail landscape mean it usually follows Singapore, not leads it.
Scoring Matrix: Eight Product Archetypes
To make the framework concrete, here are eight common craft-export archetypes scored to their strongest first market.
表格
| Archetype | Best first market | Score | Why |
|---|---|---|---|
| Craft gin | Japan | 20/25 | Premium spirits culture, high on-trade penetration, well-developed importer network — but screen your additive list against Japan's positive list before you ship. |
| Health snacks | Korea | 19/25 | Fast trend adoption, clear MFDS pathway, strong convenience-store and social-commerce channels for better-for-you products. |
| Fresh fruit | China | 14/25 | Scale is unmatched, but orchard registration (GACC Decree 280 requires registration of overseas fruit gardens and packing facilities) and phytosanitary protocol negotiation make it the longest timeline on this list. Only viable with multi-year runway. |
| Canned/preserved goods | Japan | 17/25 | Stable long-term demand, additive compliance is the gate; once an SKU is approved, reorder cycles are consistent. |
| Breakfast cereal | Korea | 18/25 | Growing breakfast-category adoption, manageable MFDS pathway, strong modern-trade presence. |
| Olive oil | Japan | 19/25 | Premium positioning, established category with strong consumer recognition of Mediterranean origin, mature importer structure. |
| Superfoods & novel ingredients | Singapore then Korea | 16/25 | Novel ingredient approval is the bottleneck in every market; use Singapore as a fast proof-point while preparing Korean functional-food dossiers. |
| Novelty confectionery | Singapore | 18/25 | Fast entry, English labels accepted, low launch cost makes it a natural test market before committing to Korea or Japan. |
Archetypes are a starting point, not a verdict. A craft chocolate made with an unusual preservative will not clear Japan even though the archetype points there; a fresh berry grower with an existing GACC-registered orchard is in a different position than one starting from zero. If you are reading your own product in this table and the recommendation feels wrong, run it past us — we will tell you which dimension is pulling the score.
To put one archetype in context: the Asia-Pacific gin market reached roughly USD 2.6 billion in retail value in 2025, growing in the high single digits year-on-year, with China the largest single market (around USD 1.1 billion) and Southeast Asia collectively approaching USD 800 million. Asia-Pacific is the fastest-growing gin region globally, driven by rising disposable incomes, urbanisation, and the spread of cocktail culture. Japan's share of that growth is disproportionately premium, which is why craft gin consistently lands there first rather than in the nominally larger Chinese market.
The Three Mistakes
1. Choosing by market size alone. China is the biggest. It is also the slowest and most complex. Size without a feasible route in is a trap. We have seen brands burn €80,000 on a China launch that was never going to clear customs, then have no budget left for a Japan or Korea launch that would have worked in six months. The 15/25 score is not a "do not enter"; it is a "do not enter first if your runway is short."
2. Assuming home-market compliance transfers. It does not. Every Asian market operates its own additive positive list, its own labelling standard, and its own producer-registration pathway. An additive approved by the FDA, EFSA, or FSANZ is not automatically approved by the NHFPC (China), MHLW (Japan), or MFDS (Korea). A label that is legal in one market can get a shipment detained or rejected in another. In Korea's 2025 imported food non-compliance cases, the top three origins for non-compliant shipments were China, Vietnam, and Thailand, but non-compliance also affected brands from highly regulated origins — the leading causes were specification violations, pesticide-residue exceedances, and food additive standard violations. The common thread was assuming the home-market formulation was acceptable as-is.
3. Skipping the scoring. Intuition feels faster. It is not. A structured score forces you to confront the dimensions you are underestimating. Brands that pick a market on gut feel almost always overweight size and underweight regulation and time-to-sale, which is exactly how you end up 18 months deep into a registration process with no revenue. The five-dimension framework takes about 90 minutes to run honestly once you have the product specification sheet and tariff codes in front of you.
Run Your Own Scoring
Take your top three candidate markets and score each one 0–5 across the five dimensions. Weight the dimensions for your own situation: cash-constrained brands over-weight Regulation and Time-to-sale; well-funded brands over-weight Size × Price; brands riding an active inbound enquiry over-weight Channel.
The highest total is your starting point. It is not a final answer — tariffs change, regulations update, distributor conversations open and close — but it is a far better first answer than "China is big, start there."
If you want a second opinion, book a free 20-minute compliance snapshot. We will score your product against the markets that fit, flag any additive or labelling issues before you spend money on samples, and tell you honestly if none of the markets you are looking at are ready for you yet.
Frequently Asked Questions FAQ
Which Asian market should a craft food or drink brand enter first?
There is no universal answer, but this article's framework gives you one. Score China, Japan, Korea, and Southeast Asia on tariff, regulation, channel, size × price, and time-to-sale, weighting Regulation and Time-to-sale higher if cash-constrained, Size × Price higher if well funded. The highest total is your starting point; for most craft brands, that's Japan or Korea first, China second.
How long does GACC Decree 280 CIFER registration take for a food facility?
Three to four weeks for a clean general-food file submitted correctly; 6–12 weeks if authorities issue a supplementary-notice request, which happens on roughly a third of first-time submissions. The 5-year auto-renewal is real but not unconditional — material changes to product scope or facility layout require an update filing.
Can I use Hong Kong as a back door into mainland China?
No. Hong Kong is a separate regulatory jurisdiction with its own FEHD labelling and registration rules. Product legally sold in Hong Kong cannot be shipped across the border into mainland China without full mainland general-trade import procedures, including GACC registration, GB 7718 Chinese labelling, and full duty. Treat Hong Kong as its own premium channel, not a detour.
Is Singapore a real revenue market for food brands?
Rarely as a first entry. Zero tariffs, English labels, and fast entry are real, but the population is under six million, and retail is saturated. Most brands use Singapore as a reference-market proof point, a regional distribution hub, and a place to build an Asian sales narrative before entering larger markets. Expect credibility, not volume.
If two markets tie on score, which one should I pick?
Go with the market where you already have an inbound enquiry or importer conversation. A lukewarm importer in a harder market beats no importer in an easier one — an interested partner is the single highest-correlation predictor of whether your first shipment actually clears and sells. With no conversations on the table, break the tie on Time-to-sale: get a first shipment and retail reference faster, then use that reference to negotiate the second market.
This article is intended as general market-access information and does not constitute professional compliance or legal advice. Regulatory requirements change; always verify the current position against the issuing authority's published documents before committing budget or production timelines. For a compliance assessment specific to your product and target markets, contact us at kevin@specitconsulting.com.
Related reading
- Importing Spirits and Alcohol Beverages to Asia: A Compliance Roadmap for Crafted Distillers
- GACC Decree 280: Two Months of Food Import Rejection Data -- What Exporters Must Fix Before Shipping
Need help navigating your market entry?
We've helped food exporters across 10+ countries enter 13 Asian markets. Get a free initial assessment based on public data — delivered in 3 working days.
Get Your Free AssessmentContinue Reading
▶Food Import Detentions in Asia: 7 Real Cases and How to Avoid Them (2026)
▶Japan Food Import Requirements: A 6-Step Compliance Guide for EU Exporters (2026)
Questions about entering the Asian market?
Chat with us on WhatsApp →